· four exchange APIs · rebuilt daily
What is a perpetual futures contract and how funding drives its cost
The finding
Funding rate spreads on perpetual futures contracts reach 0.0362 percentage points per eight hours between exchanges for the same asset.
Arthur Hayes and BitMEX created the perpetual swap in 2016 to eliminate monthly contract expiry dates.
Long positions pay funding directly to shorts when perpetual prices trade above index mark prices.
Choosing a venue with lower funding rates prevents position capital decay over extended holding periods.
Core mechanics of what is a perpetual futures contract
A perpetual futures contract is a derivative instrument without an expiration date. Understanding what is a perpetual futures contract requires looking at the periodic funding mechanism that forces contract prices back to spot index levels. Financial markets operated on fixed monthly delivery dates for centuries before Arthur Hayes and BitMEX introduced the perpetual contract in 2016. The contract is an engineering choice designed for continuous crypto trading rather than an immutable law of financial markets. Traditional futures converge to spot prices upon settlement dates, whereas perpetual contracts maintain price alignment through ongoing peer-to-peer cash transfers.
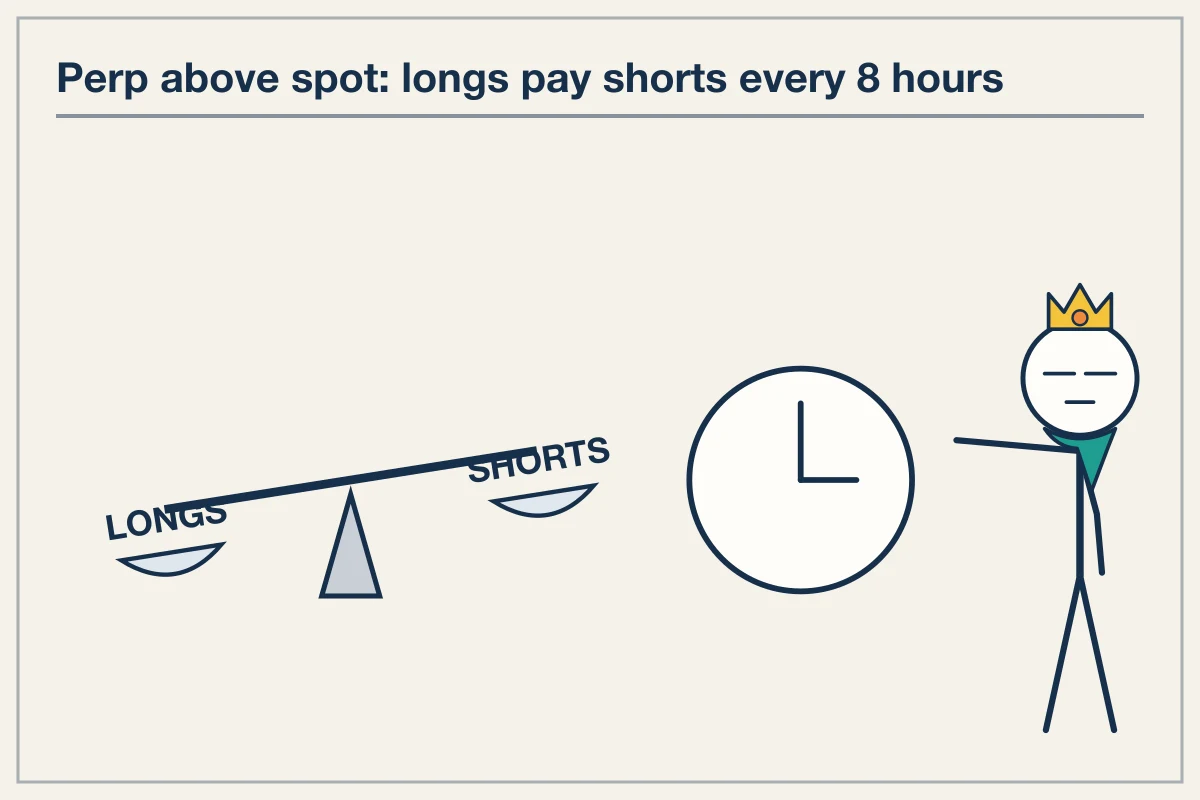
When long demand drives perpetual prices above the underlying spot index, the funding rate turns positive. The exchange requires long position holders to pay a funding fee directly to short position holders every eight hours. If aggressive selling pushes the perpetual price below the index price, the funding rate turns negative and short position holders pay long position holders.
Worth knowing
Exchanges do not collect or keep funding payments; capital transfers take place directly between long and short position holders on the order book.
Funding arithmetic and holding cost calculations
Funding rates adjust relative positioning costs across long and short market participants. On ETH, BTC, and ZEC, default funding rates across Bybit, Bitget, MEXC, and OKX sit at +0.0100% per eight-hour interval. This baseline rate equals 0.0300% daily, which translates to an annual holding cost of 10.95% on position value before applying leverage.
When market demand skews directionally, exchange rates diverge. Consider a trader holding a $100,000 long position in SOXL perps over a 30-day period.
Where this goes wrong
High positive funding rates compound against long positions during sideways market consolidation, shrinking liquidation buffers.
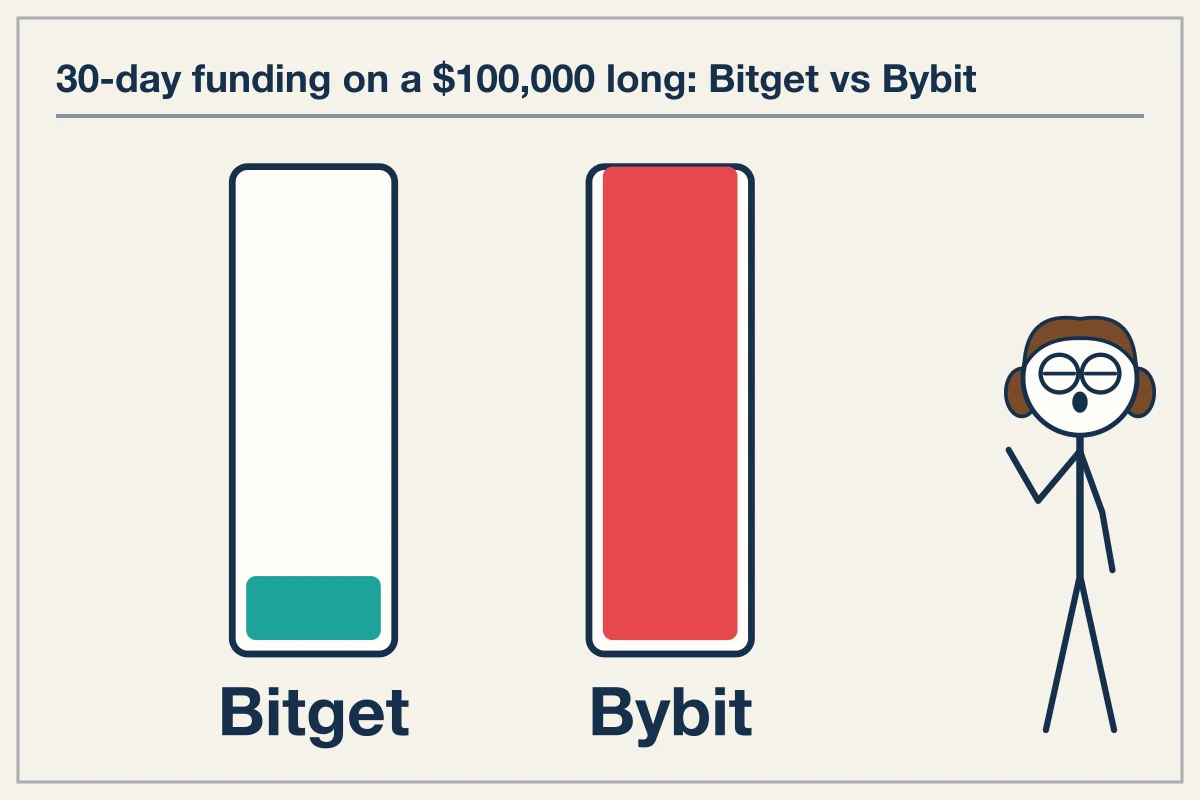
On Bybit, the SOXL funding rate is +0.0254% per eight-hour interval. The daily funding cost is 0.0762%, which equals $76.20 per day. Holding this $100,000 position for 30 days costs $2,286.00 in cumulative funding fees.
On Bitget, the SOXL funding rate is +0.0616% per eight-hour interval. The daily funding cost is 0.1848%, which equals $184.80 per day. Holding the identical $100,000 position on Bitget for 30 days costs $5,544.00. The funding rate spread between these venues creates a $3,258.00 cost gap over one month on the exact same nominal trade.
Live venue funding rates and execution fee comparison
Holding expenses combine periodic funding transfers with initial execution fees. Maker and taker fees determine execution drag on entry and exit, while 8-hour funding rates control ongoing position maintenance.
| Asset | Venue | 8h Funding Rate | Futures Maker Fee | Futures Taker Fee | 24h Volume |
|---|---|---|---|---|---|
| ETH | Bybit | +0.0100% | 0.0200% | 0.0550% | $6,073,986,117 |
| ETH | OKX | +0.0100% | 0.0200% | 0.0500% | $6,073,986,117 |
| ETH | Bitget | +0.0100% | 0.0200% | 0.0300% | $6,073,986,117 |
| ETH | MEXC | +0.0100% | 0.0000% | 0.0200% | $6,073,986,117 |
| SOL | Bitget | +0.0072% | 0.0200% | 0.0300% | $949,676,024 |
| SOL | OKX | +0.0091% | 0.0200% | 0.0500% | $949,676,024 |
| SOL | Bybit | +0.0100% | 0.0200% | 0.0550% | $949,676,024 |
| SOL | MEXC | +0.0100% | 0.0000% | 0.0200% | $949,676,024 |
| SOXL | Bybit | +0.0254% | 0.0200% | 0.0550% | $593,017,530 |
| SOXL | OKX | +0.0279% | 0.0200% | 0.0500% | $593,017,530 |
| SOXL | MEXC | +0.0465% | 0.0000% | 0.0200% | $593,017,530 |
| SOXL | Bitget | +0.0616% | 0.0200% | 0.0300% | $593,017,530 |
What to do instead
Check live funding rate spreads across platforms before entering multi-day swing positions.
Exchange fee schedules modify total execution costs. MEXC sets futures maker fees to 0.0000% and taker fees to 0.0200%. Bitget charges 0.0200% maker and 0.0300% taker fees. OKX charges 0.0200% maker and 0.0500% taker fees. Bybit sets default rates at 0.0200% maker and 0.0550% taker fees.
On SOL, holding a long position on Bitget incurs an 8-hour rate of +0.0072%, compared to +0.0100% on Bybit. For a $50,000 position held over 10 days (30 intervals), Bitget funding costs $108.00 while Bybit funding costs $150.00. Adding transaction fees, an entry taker order costs $15.00 on Bitget versus $27.50 on Bybit.
What is a perpetual futures contract?
A perpetual futures contract is a derivative with no settlement date that tracks an underlying asset index. It uses cash transfers called funding payments between long and short traders to pull contract prices back to spot levels.
How often are perpetual contract funding fees settled?
Most derivatives exchanges settle funding payments three times per day at eight-hour intervals. These periodic transfers apply directly to account balances based on position size at the exact timestamp of settlement.
Who receives perpetual funding payments?
Funding fees transfer directly between market traders on an exchange. When funding rates are positive, long position holders pay short position holders; when funding rates are negative, short position holders receive payments paid by long position holders.
Why do perpetual funding rates differ across exchanges for the same coin?
Funding rates depend on individual order book balance and long-to-short leverage ratios per exchange. Localized buying or selling pressure on one exchange causes perpetual prices to drift further from spot index prices than on competing platforms.